Date: Tuesday, November 10, 2026
Attendees: Ujin Chung (CEO), Hyunsik Ahn (CFO), Donghoon Kim (CEO of NHN Cloud)
Agenda: NHN Q3 2026 Earnings & Future Strategy
■ Executive Summary: NHN Q3 2026 Earnings & Business Highlights
▣ Q3 2026 Financial Highlights
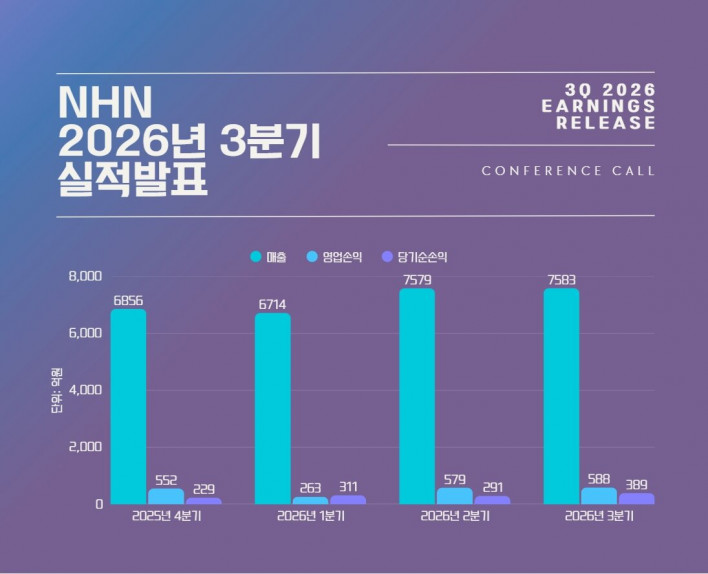
- Q3 2026 Revenue: 758.3 billion won (+21.2% YoY, +0.1% QoQ)
└ Sustained growth momentum in Payment and Technology divisions
└ Technology division grew 53.6% YoY
- Operating Profit: 58.8 billion won (+112.6% YoY, +1.5% QoQ)
└ Operating margin of 7.8%, up 3.3%p YoY
- Net Profit: 38.9 billion won (+115.8% YoY, +33.6% QoQ)
└ Increased QoQ due to lower corporate tax expenses despite ongoing non-operating losses
└ Net profit margin of 5.1%
- Q3 2026 Revenue by Business Division
└ Gaming: 131.0 billion won (+10.7% YoY, -6.2% QoQ)
└ Payment: 397.6 billion won (+21.5% YoY, +0.9% QoQ)
└ Technology: 171.7 billion won (+53.6% YoY, +7.5% QoQ)
└ Others: 78.5 billion won (-12.4% YoY, -10.8% QoQ)
▣ Gaming Business Status
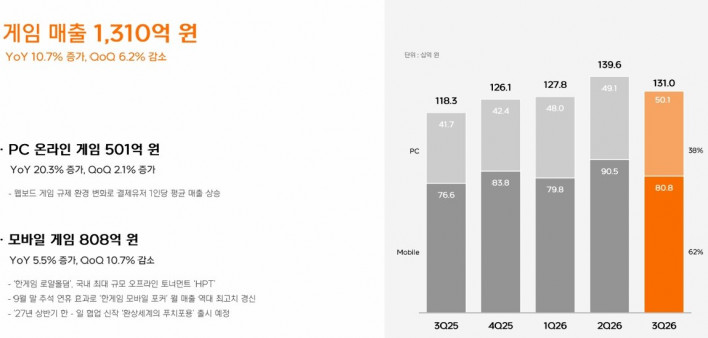
- Q3 2026 Gaming Revenue: 131.0 billion won (+10.7% YoY, -6.2% QoQ)
- PC Online Gaming Revenue: 50.1 billion won (+20.3% YoY, +2.1% QoQ)
└ Average revenue per paying user (ARPPU) increased due to regulatory changes in web-board games
└ Accounted for approximately 38% of total gaming revenue
- Mobile Gaming Revenue: 80.8 billion won (+5.5% YoY, -10.7% QoQ)
└ 'Hangame Royal Hold'em' hosted 'HPT', Korea's largest offline poker tournament
└ 'Hangame Mobile Poker' set an all-time monthly revenue record driven by late September Chuseok holiday traffic
└ Accounted for approximately 62% of total gaming revenue
- Future Gaming Roadmap
└ Co-developed Korea-Japan title 'Fantasy World's Puchipoyong' scheduled for launch in 1H 2027
└ Continued development of popular Japanese mobile titles via NHN PlayArt
▣ Payment Business Status
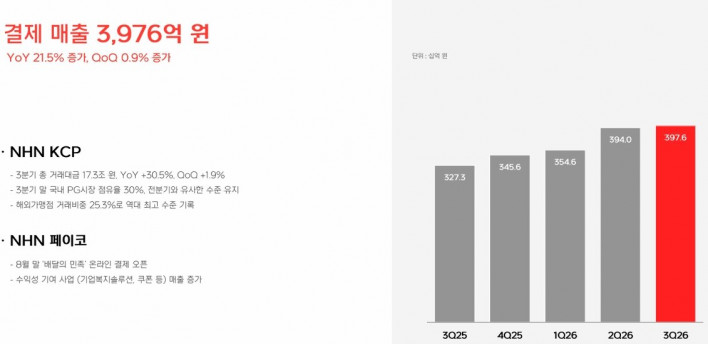
- Q3 2026 Payment Revenue: 397.6 billion won (+21.5% YoY, +0.9% QoQ)
- NHN KCP
└ Q3 Total Payment Volume (TPV): 17.3 trillion won (+30.5% YoY, +1.9% QoQ)
└ Maintained domestic PG market share at approximately 30% as of Q3 end, flat QoQ
└ Overseas merchant transaction ratio reached a record high of 25.3%
- NHN PAYCO
└ Launched online payment services on 'Baedal Minjok' in late August
└ Revenue grew in high-margin segments including corporate welfare solutions and coupon services
▣ Technology Business Status
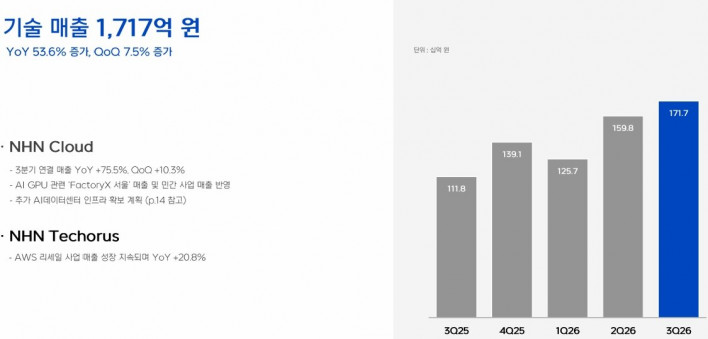
- Q3 2026 Technology Revenue: 171.7 billion won (+53.6% YoY, +7.5% QoQ)
- NHN Cloud
└ Consolidated revenue up 75.5% YoY and 10.3% QoQ
└ Recognized revenue from AI GPU-related 'FactoryX Seoul' and private enterprise cloud projects
└ Pushing to secure additional AI data center infrastructure
- NHN Techorus
└ Sustained revenue growth in AWS reselling business
└ Revenue up 20.8% YoY
▣ Other Businesses & Operational Efficiency
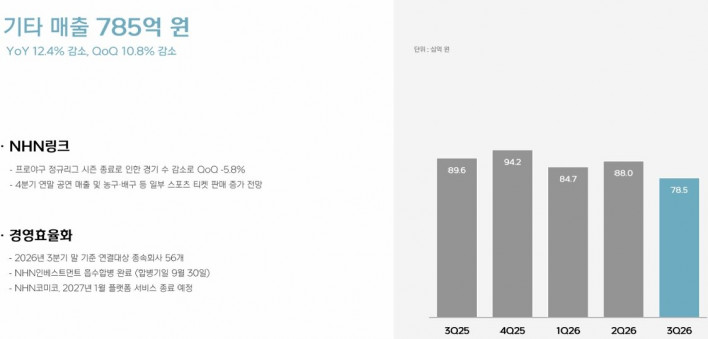
- Q3 2026 Other Business Revenue: 78.5 billion won (-12.4% YoY, -10.8% QoQ)
- NHN Link
└ Revenue fell 5.8% QoQ due to fewer matches following the end of the KBO regular season
└ Ticket sales expected to rebound in Q4 driven by year-end concerts and indoor sports (basketball, volleyball)
- Operational Efficiency Measures
└ 56 consolidated subsidiaries as of the end of Q3 2026
└ Completed merger with NHN Investment (effective date: September 30)
└ NHN Comico platform service scheduled to shut down in January 2027
▣ Q3 2026 Operating Expenses Breakdown
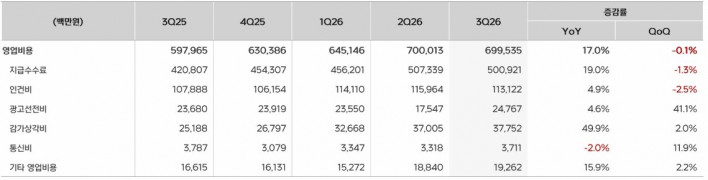
- Q3 2026 Operating Expenses: 699.5 billion won (+17.0% YoY, -0.1% QoQ)
- Commission Expenses: 500.9 billion won (+19.0% YoY, -1.3% QoQ)
└ Decrease in revenue-linked fees and publishing commissions related to NHN PlayArt games
- Labor Costs: 113.1 billion won (+4.9% YoY, -2.5% QoQ)
└ High base effect resulting from bonus payouts in certain business units during the previous quarter
- Marketing Expenses: 24.8 billion won (+4.6% YoY, +41.1% QoQ)
└ Increased marketing spend for web-board games
└ Reflected offline marketing costs including Tokyo Game Show (TGS) participation and hosting the HPT tournament
- Depreciation & Amortization: 37.8 billion won (+49.9% YoY, +2.0% QoQ)
└ Partially reflected depreciation for newly deployed B300 GPUs in Q3
- Network Costs: 3.7 billion won (-2.0% YoY, +11.9% QoQ)
- Other Operating Expenses: 19.3 billion won (+15.9% YoY, +2.2% QoQ)
└ Higher electricity utility expenses related to NHN Cloud's government AI GPU projects
▣ AI GPU Data Center Expansion Roadmap
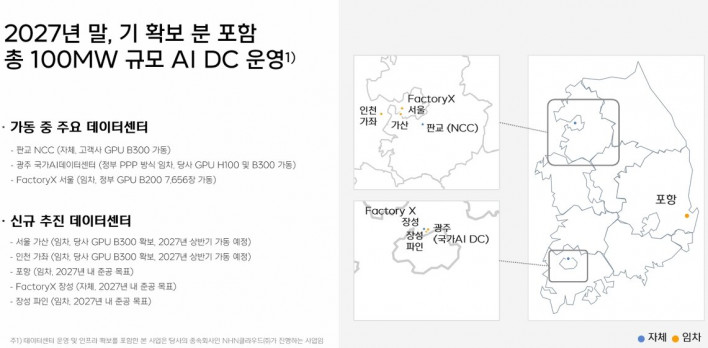
- Plan to operate a total of 100 MW in AI data center capacity by the end of 2027, including existing facilities
└ Based on NHN Cloud initiatives, including data center operations and infrastructure procurement
- Key Currently Operational Data Centers
└ Pangyo NCC: Proprietary data center operating client B300 GPUs
└ Gwangju National AI Data Center: Leased via government PPP model, operating H100 and B300 GPUs
└ FactoryX Seoul: Operating 7,656 government-backed B200 GPUs
- Pipeline / Upcoming Data Centers
└ Seoul Gasan: Leased facility, B300 GPUs secured, scheduled to open in 1H 2027
└ Incheon Gajwa: Leased facility, B300 GPUs secured, scheduled to open in 1H 2027
└ Pohang: Leased facility, targeted for completion within 2027
└ FactoryX Jangseong: Proprietary data center, targeted for completion within 2027
└ Jangseong Pine: Leased facility, targeted for completion within 2027
▣ Shareholder Return Policy & Corporate Updates
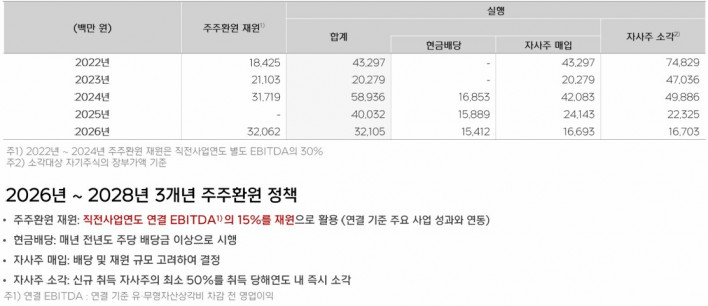
- Executing a three-year shareholder return policy from 2026 to 2028
└ Allocating 15% of consolidated EBITDA from the preceding fiscal year for shareholder returns
└ Maintaining cash dividend per share at or above the previous year's level annually
└ Share buyback scale determined in consideration of dividend payouts and total available funding
└ Immediate cancellation of at least 50% of newly acquired treasury shares within the acquisition year
- 2026 Shareholder Return Execution Status
└ Total shareholder return pool: approx. 32.1 billion won
└ Cash dividends: approx. 15.4 billion won
└ Share repurchases: approx. 16.7 billion won
└ Share cancellations: approx. 16.7 billion won
- Workforce Status (As of end of Q3 2026)
└ Total head count: 4,361 employees, up 111 QoQ
└ Reflected workforce expansion at certain subsidiaries and business unit reorganizations
You announced plans to expand AI data center capacity to around 100 MW by the end of 2027. What are your projections for revenue growth and profitability following this expansion? As the proprietary GPU business grows, costs such as depreciation are also expected to rise; could you provide more context on this? Additionally, web-board gaming revenue has been rising — what is your outlook for Q4 and next year?
Hyunsik Ahn, CFO: The GPU business still involves many variables, so while we are modeling revenue outlooks through various methods, it is difficult to provide exact figures at this stage. However, we can shed some light on our profitability outlook.
Based on our operating experience so far, we are consistently generating close to a 30% margin on a direct cost basis. As GPUs are upgraded to newer generations in the future, we expect efficiency to improve even further.
Donghoon Kim, CEO of NHN Cloud: Power capacity is around 6 MW, and as mentioned earlier, we plan to deploy approximately 1,700 B300 GPU units. This infrastructure will sequentially enter full service starting from December through the end of January next year.
Ujin Chung, CEO: For web-board games, we expect the revenue gains driven by regulatory easing in 2026 to carry over into 2027. However, we anticipate the actual pace of revenue growth to moderate somewhat.
Nevertheless, there is a clear reason why we are focusing on Hold'em tournaments like the HPT. The Hold'em player demographic is somewhat distinct from traditional poker players. Our goal for 2027 is to expand the Hold'em market to a scale comparable to the existing poker market, built on a healthy offline tournament culture.
While we cannot firmly guarantee a revenue growth rate exceeding 10% through this, you can understand our target as striving to achieve growth close to that level.
Do you plan to participate in government AI GPU projects again next year? Could you elaborate on the government's future direction and NHN Cloud's corresponding strategy?
Donghoon Kim, CEO of NHN Cloud: Next year, the government is expected to pursue projects worth around 4 trillion won, procuring hardware equivalent to or exceeding NVIDIA's latest 'Vera Rubin' architecture. We are preparing with plans to participate in projects that utilize this infrastructure as well.
In addition, all of our newly developed data centers are being secured as facilities capable of supporting liquid cooling systems to accommodate Vera Rubin deployments. You can view this as proactively preparing our infrastructure to support next-generation GPUs.